

“The Smokeable Products segment grew adjusted operating companies income or OCI by 2.7%. Adjusted OCI margins were 64.4%, an increase of 4.2 percentage points versus a year ago. This performance was supported by robust net price realization of 10.8%.” - Salvatore Mancuso, Altria CFO, Q1’25 remarks
The volumes. The illicits. The writedown. Take your pick; there is no shortage of salt to pour. A nasty narrative becomes easier to write, considering that modern oral, the one next-gen category that Altria has executed relatively well in, is set to face extra pressure, which is not quite yet evident in the figures. To many, Altria appears a shadow of its former self, hopelessly attempting to squeeze water from a stone. Yet, despite all of the heartache and blows to the head, the core business refuses to dry up, and the stream of free cash continues to flow into a shrinking pool of shares.
on! your mark
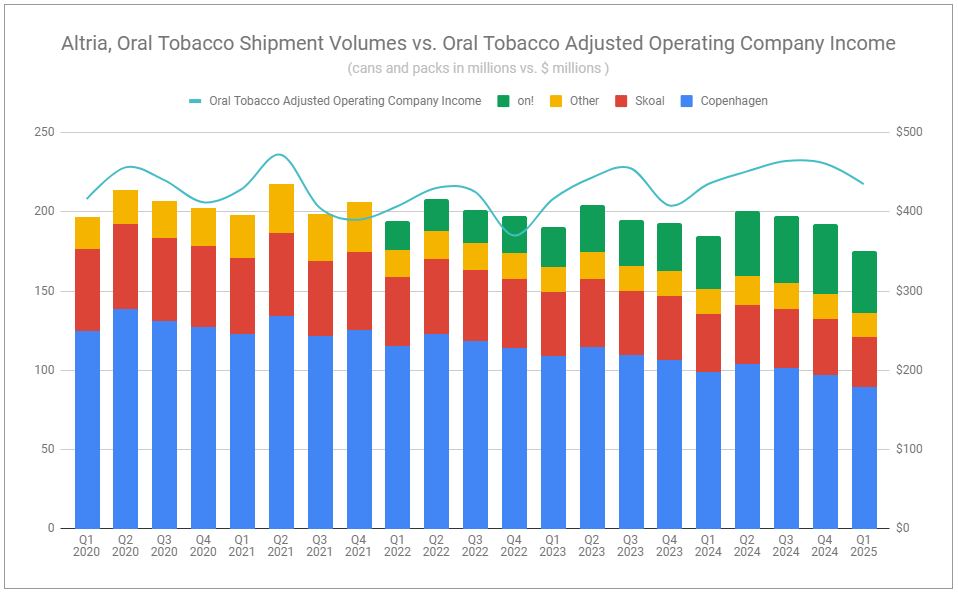
There is little doubt that the elevated volume decline in Altria’s Oral Tobacco segment, much like its smokeables, has caused the raising of eyebrows. However, adjusting for movements in trade inventory, oral volumes were down by a mere 1%. It is easily argued that this is more concerning when the oral category in the U.S. continues to grow volumes at a steady clip. Altria’s dominant position in legacy continues to be eaten away by nicotine pouches at an increasing rate, and its share of the total market paints a picture far more alarming than the rest of the figures support.
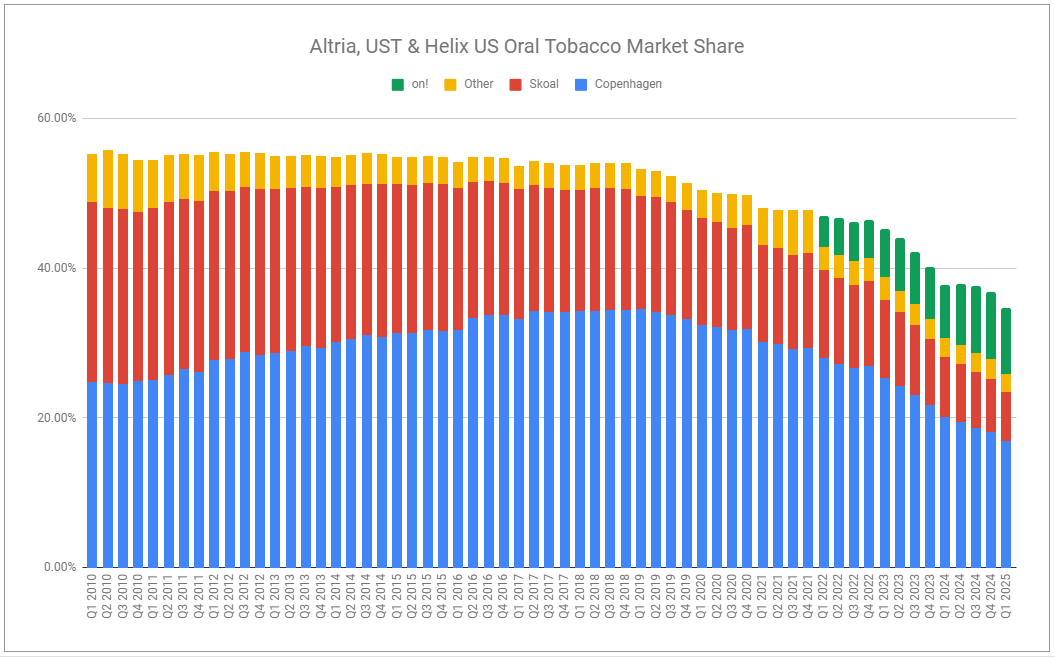
Punch in the numbers, and revenues net of excise were marginally higher in Q1’25, while adjusted income for the segment was flat. Some will interpret this as stagnation, which will be inferred to signal the inevitable shift to decline. All that I am sure of is that single quarters can be noisy, and balancing share, volume, and price is more complicated than merely hitting a few strokes into the system.
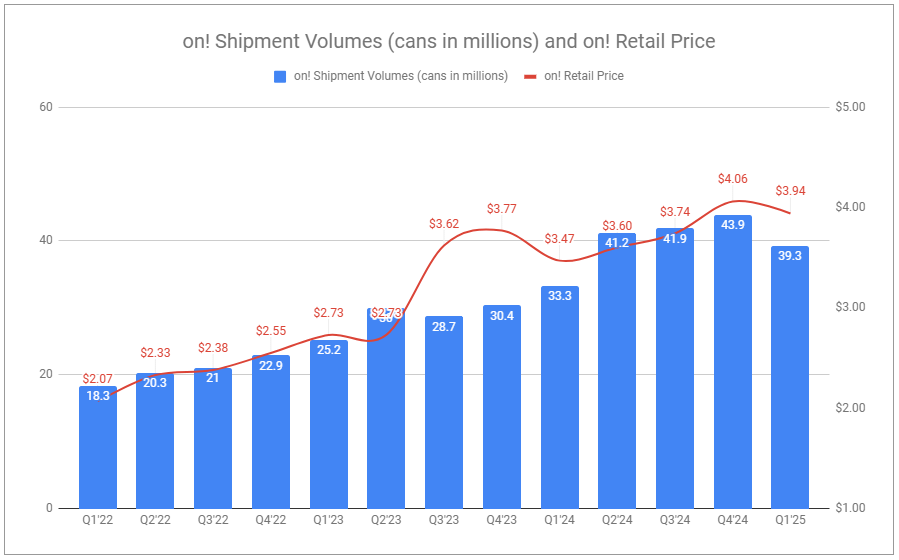
Shipment growth of on! at 18% is far from eye-catching relative to others in the nicotine pouch space, but is nothing to scoff at. Yet, it not only shows a marked drop sequentially, but also the lightest in the last four quarters. In addition, average retail pricing for the product also dropped sequentially, reflecting softening prices, varying promotions, and bundling. Much of this could be chopped up as noise when looking out further, as the category continues to grow at a heady clip.
The tools and levers are in place for Altria to balance the drivers of profits, but growth in absolute terms must be questioned. Just as in last week’s piece covering Philip Morris International, in which I raised blasphemous questions toward ZYN in the U.S., actual threats are emerging in the U.S. nicotine pouch space that I believe will weigh against Altria, too. Unlike PMI’s management, which cited competitors engaging in higher degrees of promotion, Altria got closer to the point when asked by Barclays’ Gaurav Jain (emphasis added):
And my second question is on on!. So still pretty robust growth, 18% Y-o-Y but clearly, growth has slowed down, and we have the biggest competitor increasing guidance. Last week, they're more bullish. So do you think there is a risk to on!'s trajectory as we go into the second half of the year? And do you need to pursue a multi-brand strategy, maybe enter synthetic nicotine? So could you just help us understand how you're thinking about on!?
William Gifford, Altria CEO:
Yes, I'll try to disassemble, there are a couple of questions in there, and I'll try to answer them individually. I think, look, we're pleased with the on!. Some of it is just mathematical, as the base grows, then certainly from a percentage standpoint, it's going to slow a bit. But it's a competitive marketplace.
We're certainly seeing the entry of various, as you mentioned, synthetic nicotine products into the marketplace with different traits to the consumer and the consumers are trying those. But we're pleased with it. And I would highlight, again, back to our pipeline. We're excited for authorization for on! PLUS to bring it to the marketplace.
Certainly, it was the adult dipper that moved first, and they were desiring something a bit larger from a pouch perspective. And so we're excited to be able to bring on! PLUS and we feel good about on! and we'll continue to drive its momentum in the marketplace.
on! is differentiated in both can and pouch formats, and clearly appeals to select groups of adult consumers. But the introduction of new competing brands (with Velo Plus leading), which are growing quickly due to their high quality and aggressive discounting, is actively altering the landscape. It is far more likely that these new brands will continue to outpace the category. Incumbents, including on!, will face a steeper uphill battle.
Altria’s management can express how excited they are about on! Plus all they want. There is no definitive timeline of when its pending PMTA is determined upon by the FDA, and it is even less clear if it would receive a positive outcome. With that said, I recently got my hands on the product and can provide some perspective.
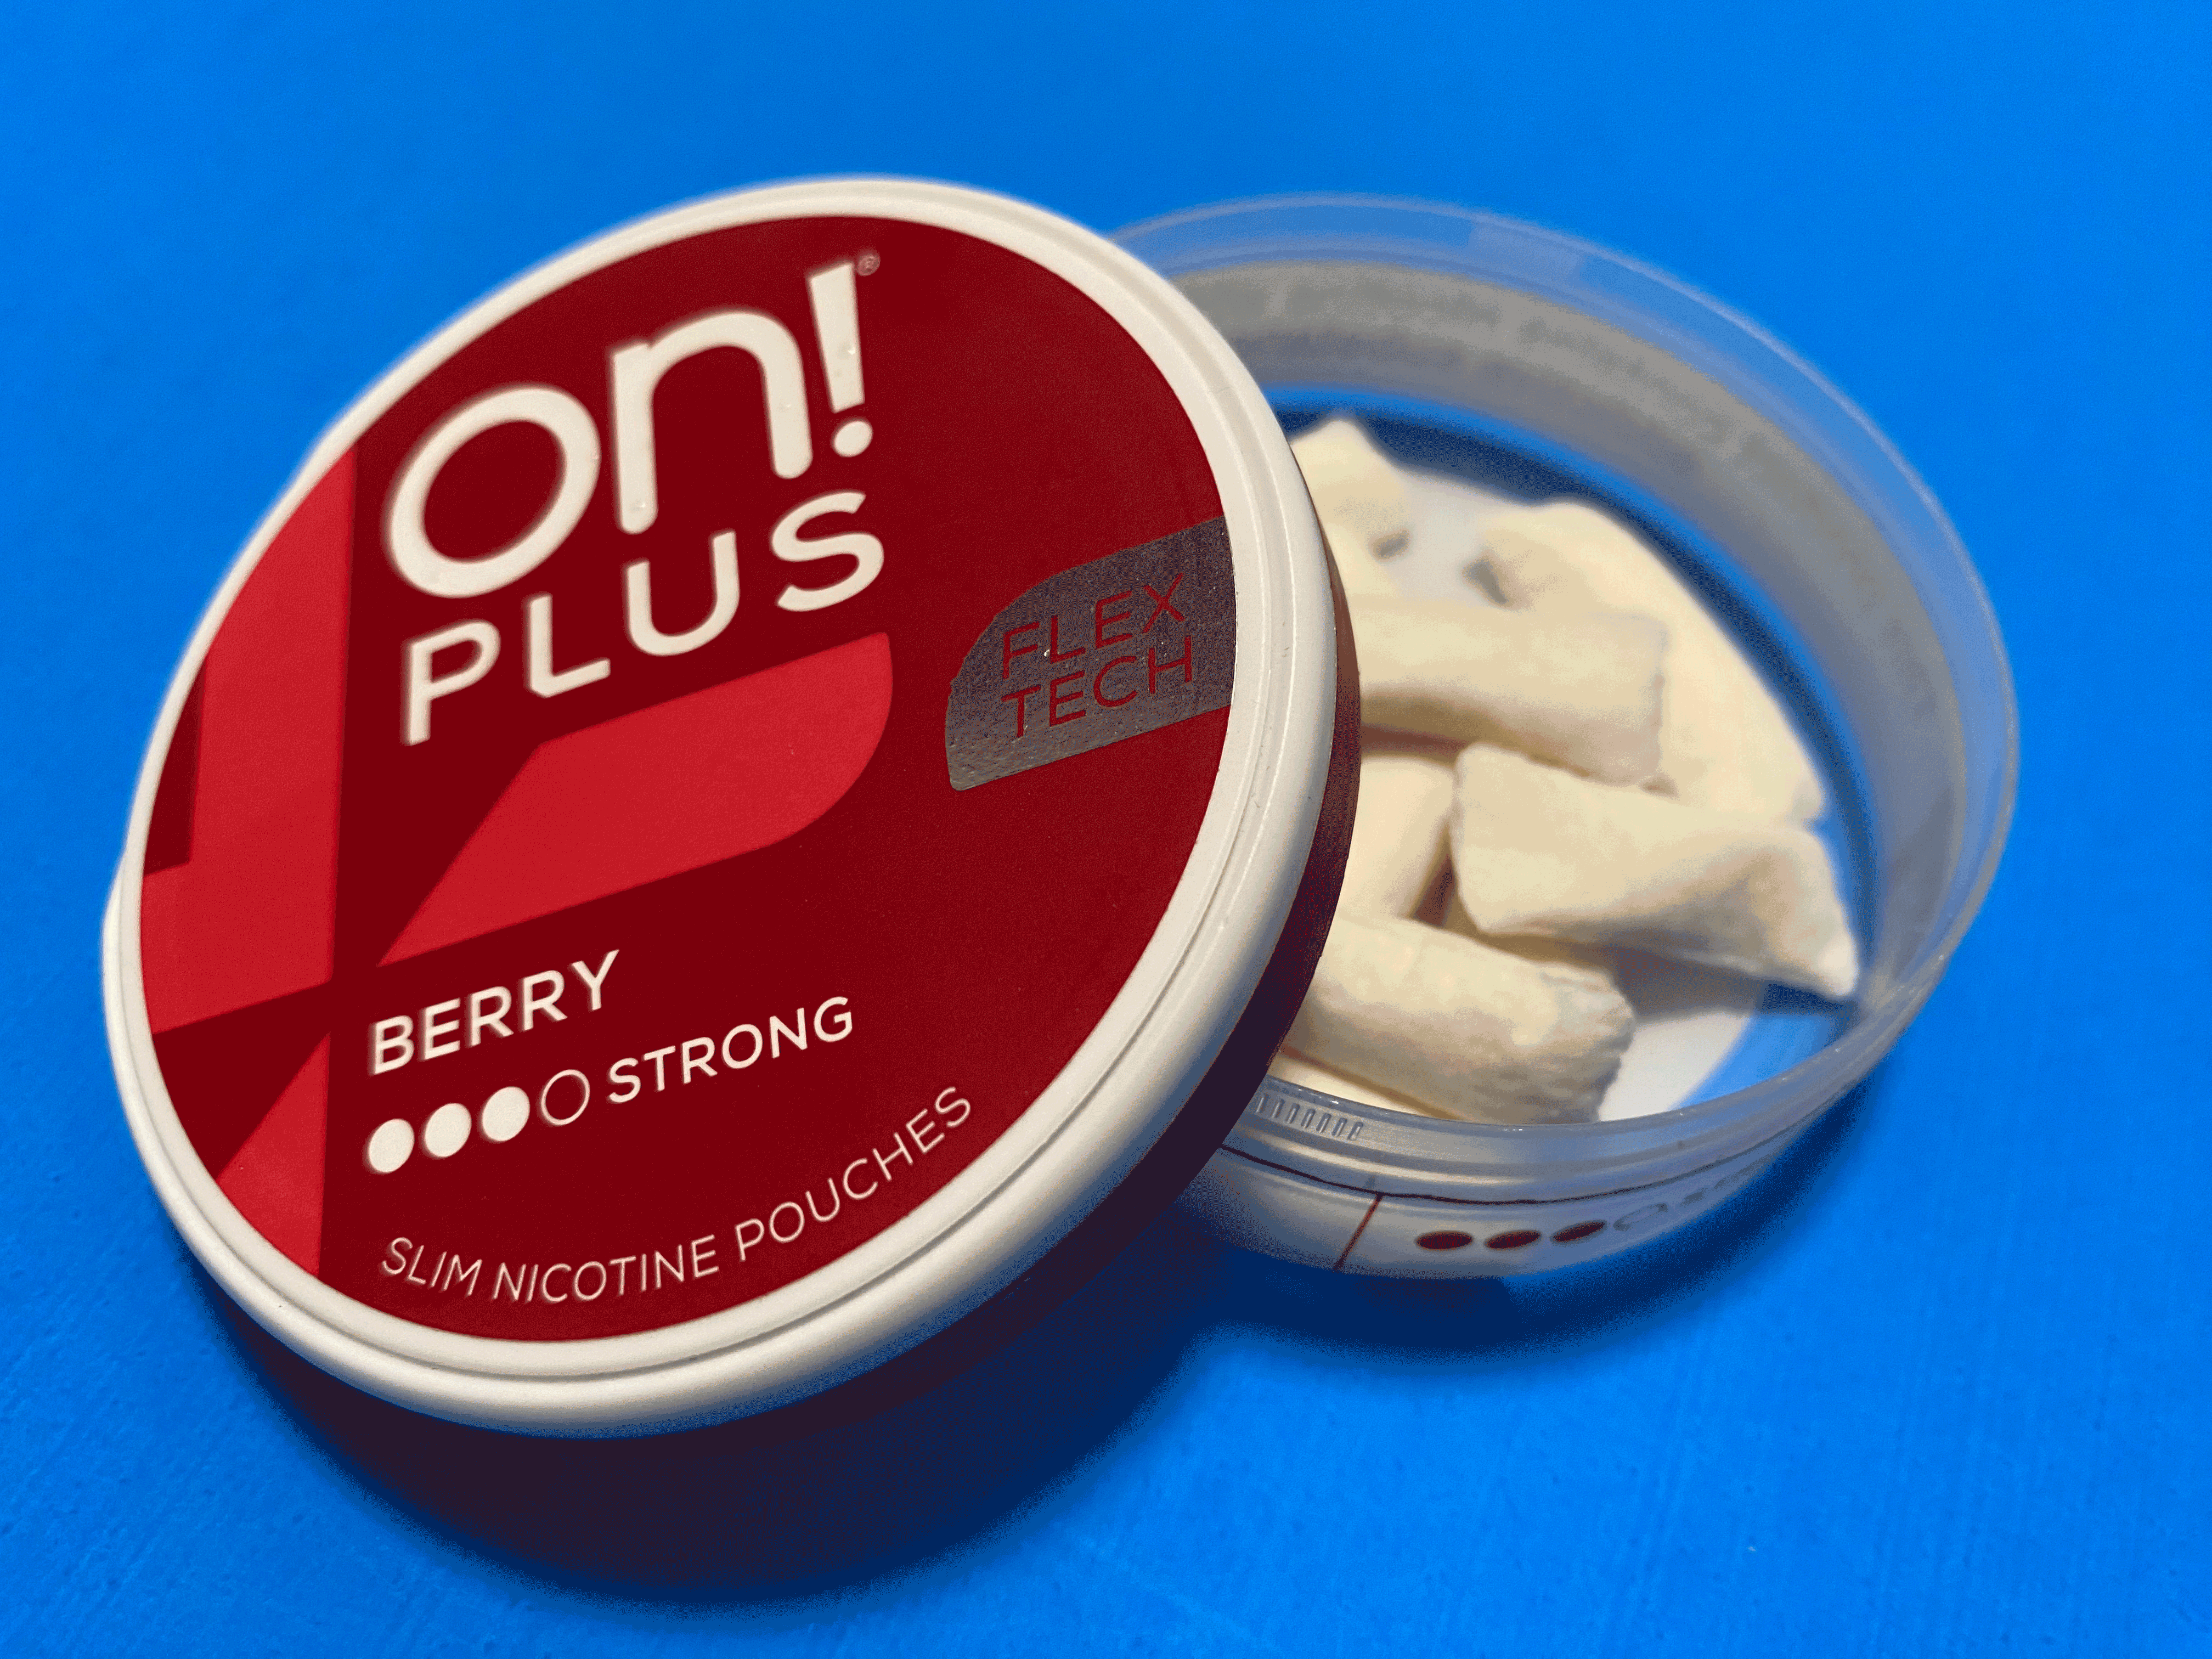
Unlike on!’s packaging, on! Plus’s is completely undifferentiated from new products in the U.S., such as BAT’s Velo Plus and Imperial’s zone, and mirrors the standard high-quality packaging seen throughout Scandinavia. However, the pouches themselves are unmistakably unique. The group’s proprietary ‘Flex Tech’ mesh material lives up to the claims made: it is one of a kind, sporting both extreme pliability and durability. The pouches are so lightweight that holding one feels close to holding nothing at all. They are the nearest embodiment of “lip pillows” you will come across in any market and are perhaps the most comfortable pouch developed to date. Their initial nicotine delivery is slightly slower than expected, considering the product’s strength, but the duration is solid. Likewise, the flavors are a different assortment that would complement the existing on! portfolio, though they are on the mild side. If this product were to enter the U.S. market eventually, it would have no problem standing out amongst the current competition. By the time that were to happen, there are good odds that many other new high-quality products would also be in the market, so there is no sense in judging further.
Add it to the pile
If you were working on a movie script, Altria’s involvement with NJOY is the type of thing so far-fetched that your editor may tell you to either scrap it due to its lack of believability or retool your work as a fantasy. What do you mean this company disposed of its partial stake in JUUL and acquired a competing company in full, only to have the new company thwarted by the old? Add it to the pile of Altria’s many mistakes.
Of course, management remains ‘hopeful’, stating that NJOY will appeal, and that, aside from the recent events concerning NJOY ACE, the capabilities acquired provide the group with the ability to innovate novel vapor products. Uncertain of all related potential outcomes, I’ll be discounting all of this hope to zero. Consider, during the Q1’25 call, management stressed how much the vapor space has changed in the U.S. since NJOY was acquired, blaming illicit products and a lack of adequate enforcement. Are they so surprised by what has developed? Two years ago, immediately following the announcement that Altria would be acquiring NJOY, before the deal was closed, the proliferation of illicit disposal vapes that would serve as a counter to the group’s rationale was highlighted. Surely they saw what was unfolding as well.