

“We continue to generate strong cash returns. We expect to be within our 2 to 2.5x target leverage corridor by year-end, while continuing to reward our shareholders with our progressive dividend and GBP 1.3 billion share buyback in 2026. I'm encouraged by the momentum we are building as we transform BAT. New categories are becoming an increasingly meaningful contributor to group performance, reinforcing our confidence in sustainable delivery moving forward.” - Tadeu Marroco, BAT CEO, H1’26 Remarks
British American Tobacco’s pre-close remarks for H1’26, published in June, were extensive. We are now armed with concrete figures following the release of the full H1 report. While we may be able to walk through these numbers and draw various conclusions, they are only part of the story. The biggest standing point is that the narrative, as a whole, is becoming so much cleaner.
It feels like just yesterday, but it was, in fact, two and a half years ago, that I wrote about BAT’s identity crisis. The company was failing to stand out relative to its peers. This was not for a lack of unique features. The company held its ITC stake. New Categories were ahead of schedule. Yet, a dark cloud hung over. New Categories demanded further investment, and the company appeared quite spread across. At the same time, the real driver of profits, combustibles, looked neglected. All the more damaging, under the guise of the looming menthol ban, the company had just announced a massive writedown on its U.S. cigarette portfolio. Then, on top of the mix, the company needed to deleverage, reducing excess capital returns to shareholders. I had said at the time:
Much like a man facing a mid-life crisis, in which he changes his entire aesthetic to pair with a brand-new motorcycle, British American Tobacco wants to be seen as cool and hip, deploying considerable sums into new product categories, seen as a way to revamp its image. But unlike the man, who may ditch the motorcycle after nine months, British American Tobacco remains steadfastly committed to its new initiatives. In both cases, they are likely to realize that many of their best years are ahead of them, not behind.
It was not merely the confluence of these factors that spooked investors. The problem was that the company’s communication had grown too verbose. BAT was attempting to be everything to everyone, everywhere, with practically endless words to explain each movement. Rather than clarity, such efforts provided confusion. It is with a sigh of relief that we can appreciate the message has narrowed.
British American Tobacco’s communication still runs long, but it is unmistakably more focused. There is discipline as the company has narrowed its footprint by exiting select markets and reworking others. Most importantly, the combustibles portfolio is burning more brightly. That is especially true for the United States, where a greatly improved combustibles performance was paired with twin-engine support for next-gen products.
Enforcement against illicit vapor continues to make BAT’s Vuse the top beneficiary in the United States, with volumes and revenues up double digits in H1’26. And while I have talked at length about the FDA’s recent Guidance for Industry, it has largely been framed in the context of the nicotine pouch category. Let us not forget that the guidance covers vapor, as well, and BAT is wasting no time taking advantage of that, with additional pod launches planned for Q3. These new offerings enable more direct competition with the black-market proposition: a wider variety of flavors that adult consumers desire.

The pains that exist elsewhere persist. This is no surprise, and there is little sense in rehashing last year’s trends or what was already articulated in the pre-close. Though it is worth noting, in a similar parallel to the drag that France has had on Logista, BAT’s largest problems are contained within its smallest geographic segment, APMEA. So, over time, even if those specific struggles persist, there will be a natural rebalancing, with the more glamorous parts making up a larger share of the pot. It is also worth pointing out the one category that is going very well, irrespective of what the geographic segments say overall: the global expansion of its modern oral business is a sight to behold.
British American Tobacco’s modern oral portfolio continues to lead in Sweden, the world’s most competitive and longest-established market. Growth has remained remarkable in areas such as the U.K. and Pakistan. There is an argument that, at its current size, the totality of the modern oral portfolio deserves less attention. However, the rate of growth and total scope suggest it's worth spending more time thinking of where the puck is heading. It is not just the aggregate volume growth figure, 57.5% in H1’26, that stands out. Nor is it category revenues growing by the mid-sixties. It is that so many more countries are taking the time to formally define and regulate the category, giving birth to new markets. For BAT, certain markets with little history of oral tobacco use, such as Japan and the UAE, are both flagged as meaningful incremental growth drivers. I quite doubt that these will be the last to establish such a trend.
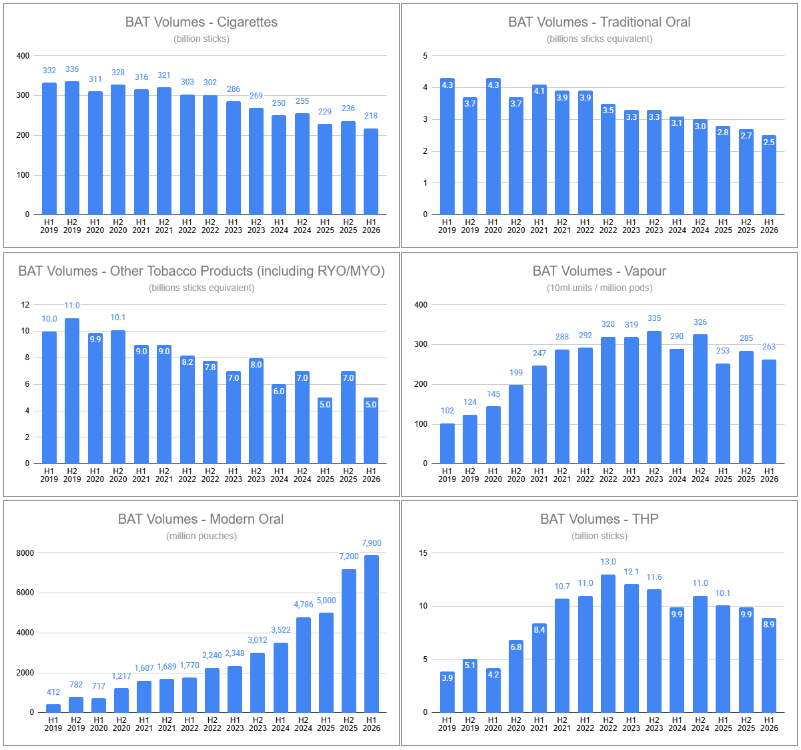
Back to the United States, although vapor is still the group’s largest next-gen category by revenues in the country, it takes a back seat to the stellar performance of the group’s modern oral portfolio. Volumes grew by 188% for the period, with revenue outpacing in both current and constant currency. This radical ascent represents capturing the majority of category growth. Yes, the launches of on! Plus and ZYN Ultra are still relatively nascent, and the FDA guidance essentially guarantees more competing launches are on the way; however, British American Tobacco is uniquely positioned on this front. The company’s execution has received much applause so far, but I suspect the cheers will grow louder still. Let us explore the confidence behind such a view.
We begin with a simple assertion: