

“The captain of a U.S. warship had all the duties and obligations of the CEO of a mid-sized corporation, and many more, since working in the civilian sector did not involve life-and-death situations. The navy was quite a change from the cigar business, but then again, it was a unique experience for practically all the men on the ship.” - Joseph F. Cullman III, I’m a Lucky Guy, p.49
Driven. To master himself. To master his work. To change the world.
Joseph F. Cullman III was born on April 9, 1912, six years older than his brother, Edgar M. Cullman. Living in New York City, he was surrounded by family members deeply entrenched in the tobacco trade. His family was better off than most, with the money and connections to give him a leg up in the world. Following the same educational path as his father, Joseph F. Cullman Jr., he attended the prominent boys’ boarding school Fessenden in Newton, Massachusetts, and Hotchkiss, a private preparatory school in Lakeville, Connecticut.
1929 was marked by several key developments. The family’s tobacco business, Cullman Brothers, was growing and profitable. That year, Joseph F. Cullman Jr. established a closed-end investment trust, Tobacco and Allied Stocks, capitalized at $3 million, with the Cullman family owning 10%. Unlike many other investment trusts at the time, it wasn’t levered or used as a speculative vehicle. Turnover was rare, with capital being steered into investments under Joseph F. Cullman Jr.’s expertise in the tobacco industry. Its largest holdings included R. J. Reynolds, American Tobacco, Imperial Tobacco, and Philip Morris. Rather than being reinvested, the dividends from these holdings were passed through to unit holders.
1929 was also a turning point for the Cullman family, marking the Cullman Brothers’ entry into cigar manufacturing. A small cigar company, Webster-Eisenlohr, was in dire straits. The company had defaulted on a loan collateralized by its own shares. The provider of that loan, Chase Bank, took control.
Chase was determined to recover the loan’s value, striking a deal to have Joseph Jr. lead Webster into profitability and, in doing so, providing him with a sizable block of preferred shares at a discounted rate. This would be no easy feat. At the time, many popular cigars were selling for five cents. With the economy souring, fewer and fewer were willing to pony up ten cents for Webster’s Golden Wedding brand, and even fewer could afford Fancy Tails, priced at fifteen cents.
In 1931, again following in his father’s footsteps, Joseph F. Cullman III attended Yale. In the summer months, between terms, is when he would cut his teeth in the tobacco trade, driving a truck for Webster and acting as a door-to-door salesman at small cigar shops. Achieving new sales was rare, and maintaining clients was a constant struggle.
When Joseph III graduated from Yale in 1935, there was no cushy job awaiting him and his ivory education. The country’s unemployment rate was ~20%. His father, believing his sons should master all aspects of the trade from the bottom up, helped him secure a role as a store clerk at Schulte’s cigar shop in New York. It was mostly unchallenging work, but in that role, he learned to connect with customers on a personal level. Unchallenged, Joseph III left his post at the cigar shop in early 1936 and was shipped off to Havana, Cuba, to learn the nuances of cigar rolling from the masters at H. Uppmann.
Joseph III returned home and excelled in sales for Webster. However, in late 1936, accusations would tilt his father, and ultimately steer him in a new direction. Joseph Jr. had successfully turned Webster profitable, but Chase Bank claimed that he was self-dealing by having the company buy cigar wrapper leaf from the family business. Jr. stepped down as CEO, and Chase sold the business. Despite the unfairness shown to his father, Joseph F. Cullman III continued to work in sales for the business until 1941, when he went on active duty in the Navy.
After the Webster incident, Joseph F. Cullman Jr. had no interest in working for any business he did not fully control. He began to eye Benson & Hedges, originally a UK company that began retailing in New York in 1899. The company was small and seemingly out of date. Its stores were ornate, staff wore morning coats, and clientele steered posh. Retailing didn't stand out to Jr.; it was the brands the company owned that did. Alongside cigars, Benson & Hedges owned several cigarette brands, each differentiated. Some were scented. Some had golden tips. Others were extra long.
Most unique to Benson & Hedges was its strategy a decade prior, at the start of the Great Depression. Understanding that consumers would be strapped for cash, many manufacturers steered heavily into cheaper brands. That makes sense, considering that industry cigarette volumes fell from ~200 billion in 1930 to 113.5 billion in 1931. B&H, however, released two new premium products. The first was Parliament, a blend of Virginia, burley, and Turkish tobaccos, flavored with licorice, apple juice, and brown sugar. Parliaments had a cardboard tip and a cotton filter, producing a uniquely smooth smoke. The second was Virginia Rounds, made from all-Virginia tobacco and encased in high-end packaging.
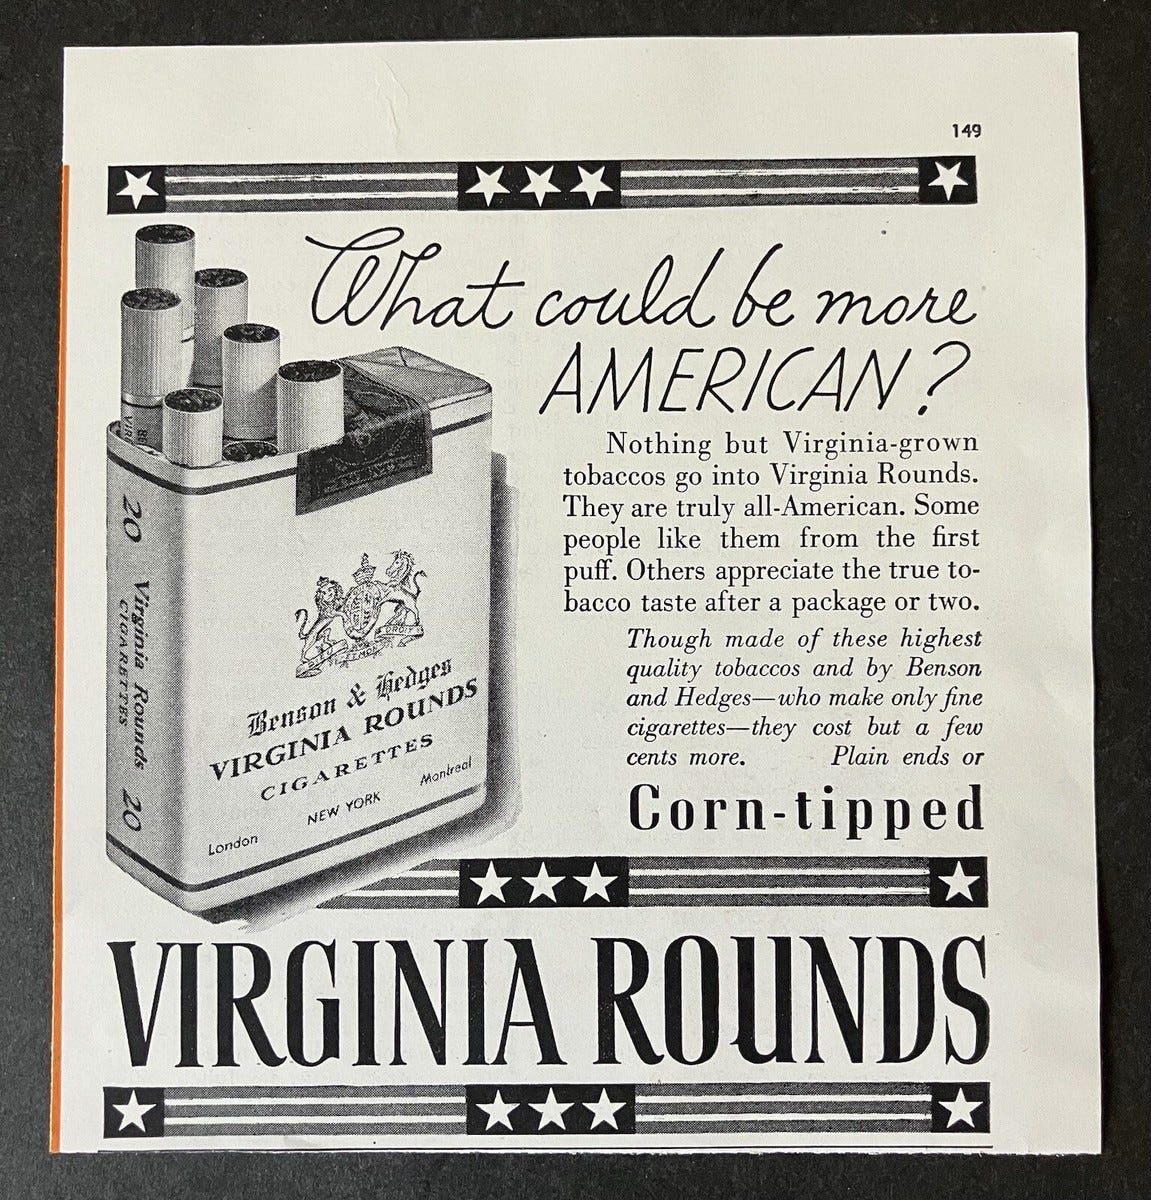
Joseph F. Cullman Jr., through Tobacco and Allied Stocks, purchased 51% of Benson & Hedges for $850,000. In 1941, B&H produced profits of $158,000 on revenues of $2.1 million. With a controlling share, Jr. had a vision to significantly increase these figures.
Joseph F. Cullman III was not yet involved in this new endeavor. In the Navy, with World War II in full gear, he found himself…rather preoccupied, to say the least. He first reported for duty on board the Reuben James, a destroyer from WWI. However, when he arrived, the commanding officer told him his assignment had changed and that he was to work at the Bureau of Navigation in Washington, D.C. This reassignment would prove to be a blessing, as the Reuben James was sunk in the North Atlantic just two weeks later, killing nearly all on board.
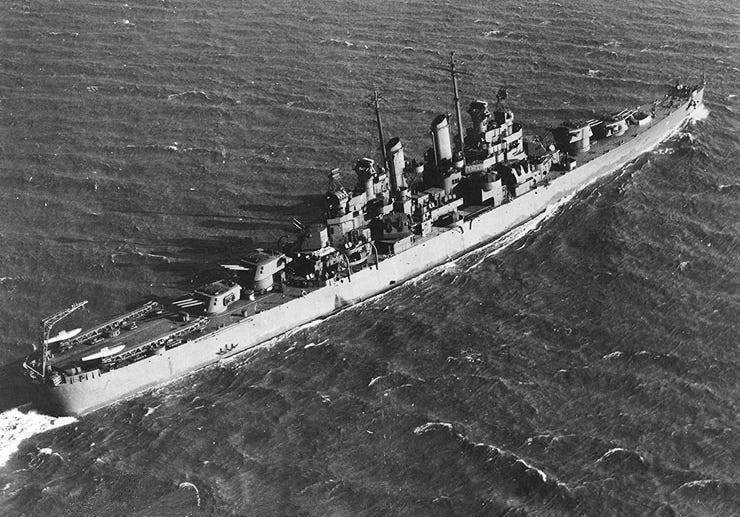
The December 7, 1941, attack on Pearl Harbor led to Joseph F. Cullman III serving on board the USS Montpelier, a Cleveland-class light cruiser, as a gunner in 1942. Unbeknownst to Joseph III at the time, the Montpelier would go on to become one of the most distinguished ships in WWII, with numerous engagements in the South Pacific over the following few years, including bombarding airfields in the Solomons, sinking a destroyer in the Battle of Blackett Strait, and partaking in the monumental Battle of Empress Augusta Bay, earning a total of thirteen battle stars.
When World War II ended in 1945, Joseph F. Cullman III was not sure what to do with himself. The family’s love for tobacco persisted, but it seemed inconsequential compared to what he experienced over the last four years. He enrolled to study history at Columbia University. This new path would not last long, as he could not resist working with his father in the industry they both knew so well.
In his absence, Benson & Hedges had flourished. The war had been an absolute boon for cigarettes. In 1945, 12 million men and women were enlisted, and military sales totaled 65 billion sticks, roughly 10% of the industry’s output. A habit had been firmly entrenched in the nation, and that year, Benson & Hedges sales rose to $5.3 million. It was time to expand, and expand they did, with Joseph F. Cullman III now serving as vice president.
The company invested heavily in increased production to keep up with demand. Sales climbed to $7.2 million in 1949 as the company began advertising in a meaningful way for the first time. Its ad budget for the year was $300,000, or about $0.50 per 1,000 cigarettes sold. In the grand scheme of things, this was still small peanuts, as the major manufacturers were spending considerably more while also selling far more cigarettes, at roughly $0.20 per 1,000 cigarettes.
The war would only be the first major tailwind for Benson & Hedges. In 1952, the article “Cancer by the Carton” was published in Reader’s Digest, raising the public’s attention to the links between smoking and lung cancer. While this created concern, it would still take more than a decade for industry volumes to reach peak levels. More importantly for B&H, smokers began to gravitate towards filtered cigarettes, which were previously only a niche category. Never mind that Parliament’s cotton filters’ real role was to prevent bits of tobacco getting stuck on smokers’ lips or in their mouths; it acted as a magnet.

In 1953, Benson & Hedges saw sales climb radically, reaching over $27 million. On these sales, the company earned a net profit of $1.2 million, roughly 7.5x what it had earned 12 years earlier when Joseph F. Cullman Jr. took control. But not all was perfect. The company had paid modest dividends in 1949 and 1950, but paid nothing in the following three years because it needed capital to expand. In 1953, the company even issued new shares, allowing existing shareholders to buy one new share at a marginally discounted price for every ten they already owned.
Further expansion would be no walk in the park. Following the Reader’s Digest article, all major manufacturers began exploring ways to make new filtered cigarettes. Despite B&H’s growth, it was still a small player. In 1953, R. J. Reynolds generated sales of $881 million, 32x more than Benson & Hedges. That same year, American Tobacco generated sales of over $1 billion.
Another tobacco company was looking to make a move. Philip Morris was an up-and-comer, having grown sales from $179 million in 1946 to $315 million in 1953. But the company could not easily go toe-to-toe with the two giants, and its R&D pipeline was lacking. An alternative path was to buy its way into the fast-growing premium filtered cigarette category.
In late 1953, Tobacco and Allied agreed to sell its majority stake in Benson & Hedges to Philip Morris. The purchase price? $22.4 million, a magnitude more than what Tobacco and Allied initially paid for its stake, paid in full with 367,829 shares of Philip Morris stock. Philip Morris’ holders would approve in April 1954.
The deal received criticism. Philip Morris paid roughly 2x the going industry multiple. Additionally, while the purchase price exceeded $22 million, Benson & Hedges had total assets of only $5.9 million. That’s quite a premium to pay for premium brands. Yet, alongside the brands and all of the production, Philip Morris gained something else deeply valuable yet overlooked: the people. People with ideas, including Joseph F. Cullman III. Parliament would remain successful. But it was merely a precursor and would soon be overshadowed by the most outstanding rebrand of all time.
In Part Two, we travel through Marlboro Country.
If you enjoyed this piece, hit “♡ like” on the site and give it a share.
Questions or thoughts to add? Comment on the site or message me on Twitter.
Ownership Disclaimer
I own positions in Altria and other tobacco companies such as Philip Morris International, British American Tobacco, Scandinavian Tobacco Group, and Imperial Brands. I also own positions in Haypp Group, a major online retailer of reduced-risk nicotine products.
Disclaimer
This publication’s content is for entertainment and educational purposes only. I am not a licensed investment professional. Nothing produced under the Invariant brand should be thought of as investment advice. Do your own research. All content is subject to interpretation.
Additional resources:
Cullman, Joseph F. III. I’m A Lucky Guy. 1998.
Robert E. Bedingfield. Personality: Tobacco Man in A Family Line; Philip Morris Chief, J.F. Cullman 3d, Heir to Dynasty. The New York Times, 1961. Source
2 BOARDS APPROVE CIGARETTE MERGER; Consolidation of Philip Morris and Benson & Hedges Now Is Up to Stockholders. The New York Times, 1953. Source