

“…there should have been an American attempt to go international before we made the move. What made the situation stranger still was the great popularity American cigarettes had enjoyed overseas during World War II. Our Soldiers took them wherever they went, and shared the smokes with Allied soldiers and civilians in Europe and the Pacific. I had seen this situation serving in the Navy, and it surprised and intrigued me. I later learned that in the early days of the occupations in Europe and Asia, our cigarettes were used as currency—but only American brands, no others. American cigarettes were preferred to money.” - Joseph F. Cullman III, I’m a Lucky Guy, p.101
Driven. To have the vision. To execute. To create a global phenomenon.
In Part Two, Joseph F. Cullman III was tasked with overseeing the creation of the new Marlboro. Painstaking efforts to refine the blend, base, box, and brand led to an all-star product. Yet, at the time, not even Cullman understood what a phenomenon it would become.
The rebirth of Marlboro coincided with the decision to expand internationally. This was unusual because it ran counter to the path domestic competitors chose. None showed much interest beyond the borders of the United States, not even R. J. Reynolds or American Tobacco, both of which were notably larger than Philip Morris at the time.
There were clear reasons why competitors decided to maintain a narrower scope. Despite increasing criticism toward the industry, the U.S. market was still growing at a steady clip and was immensely profitable. Rather than look to other markets, they preferred to prioritize domestic demand, and to hedge against the uncertain regulatory overhang, they would diversify into unrelated industries. Philip Morris would certainly do plenty of its own diversification, but its efforts in (and timing of) international expansion would ultimately prove brilliant, though the path was not without significant challenges.
Language barriers posed a significant hurdle. Culturally, there were walls to breach as well. Consumers in other countries had established preferences for cigarettes with specific types of tobaccos. Even if you could effectively overcome those challenges, many countries had manufacturing requirements, including the use of domestically-grown tobacco, not to mention the tax complexities across geographies. Overshading all of this was the fact that many attractive markets were wholly dominated by state-backed monopolies.
Philip Morris got a taste of just how difficult other markets could be in 1954, when it created its first foreign affiliate in Australia. On paper, it seemed like a sensible place to start. Australia spoke English, had an affinity for all sorts of American products, and, given its geographic proximity, could serve as a launching point for entry into Asia. However, things didn’t exactly go according to plan. Joseph F. Cullman III captured the developments hilariously well in his autobiography, I’m A Lucky Guy:
…We also sent one of our marketing people out there to help; he came up with a cartoon character called Puffing Billy in an on-premises display unit to help promote the smokes. The Philip Morris brand was a complete failure.
Another failure was Dunhill, whose trademark we licensed to use at the time. We introduced the brand in Australia, where it was greeted with complete indifference. No, that’s not right. It was absolutely rejected; the Australians called it “Dunghill.”
To add insult to injury, one familiar brand was doing quite well in Australia: Benson & Hedges. However, despite purchasing Benson & Hedges that same year, Philip Morris did not own the Australian rights to the trademark. Those rights were instead owned by British American Tobacco.
In 1955, Philip Morris branched out elsewhere, licensing La Suerte Cigar and Cigarette to produce the company’s brands in the Philippines and Tabacalera Nacional SE in Panama. This was followed by the licensing of C.A. Tabacalera Nacional de Caracas to produce Philip Morris brands in Venezuela.
A defining relationship for Philip Morris began in 1957, when it licensed Fabriques de Tabac Réunies (FTR) in Switzerland. The royalty rate equated to Philip Morris receiving less than $0.01 per pack, but the benefits of this deal extended far beyond the terms of the license. FTR was well respected in Switzerland, and Marlboro succeeded splendidly there. More importantly, it provided confidence that the company’s brands could win in Europe.
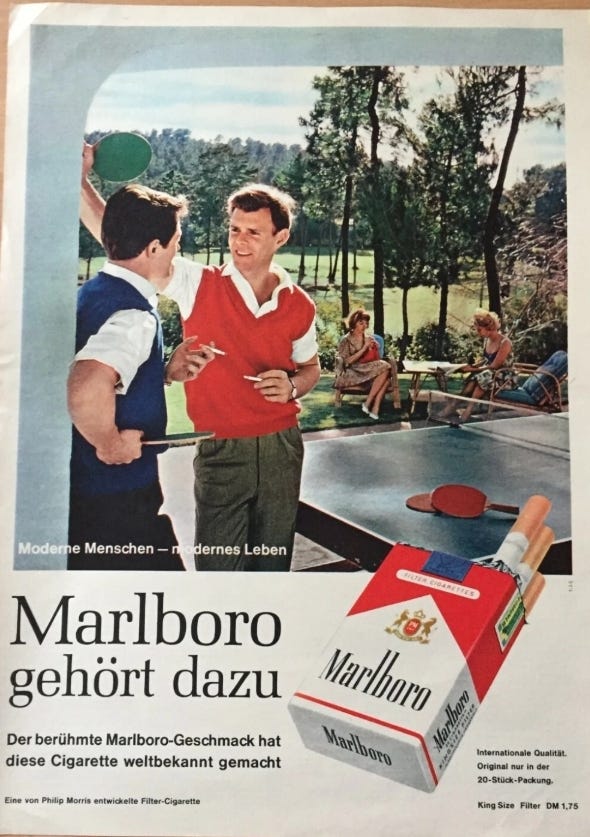
Philip Morris licensed Brinkmann to manufacture its brands in Germany in 1960, and, soon after, management spoke of respectable volume growth in the German market and anticipated more to come. However, the deal quickly highlighted the potential pitfalls of a licensing agreement. While licensing agreements reduced upfront investment costs, they led to less control, and anything less than 100% control will always prove unsatisfactory to a team that obsesses over quality. Brinkman found the tobacco blend used unsuitable for the German market, and, responsible for local marketing, believed cowboys were inappropriate for ads. Marlboro gained roughly 1% of the German market, but was stuck there for years as Philip Morris was bound by its agreement with Brinkman, grossly underperforming the brand in neighboring markets.
1961 marked the start of a string of monumental developments. The French tobacco monopoly, SEITA, agreed to sell Marlboro in designated stores and struck a licensing deal with Philip Morris to produce Parliament. The company’s 1961 Annual Report expounds on good and bad alike:
NEW LICENSING AGREEMENTS SIGNED; In France, Parliament was successfully introduced under a manufacturing license arrangement with the French Government Regie. In Benelux, Philip Morris is being manufactured under a licensing arrangement made late in 1961 with Ed. Laurens "Le Khedive." Marlboro will be introduced in Finland in 1982, to be made there by Amer-Tupakka Qy, under license from Philip Morris.
In South America, Philip Morris brands have a wide acceptance and our sales in this important market increased in 1961. In the Far East we enlarged our position, especially in Hong Kong where Philip Morris, locally made to our quality standards, were successfully introduced. In the Philippines, sales of our locally made Philip Morris and Marlboro brands were sharply curtailed at year's end by restrictions on the Importation of American grown tobaccos.
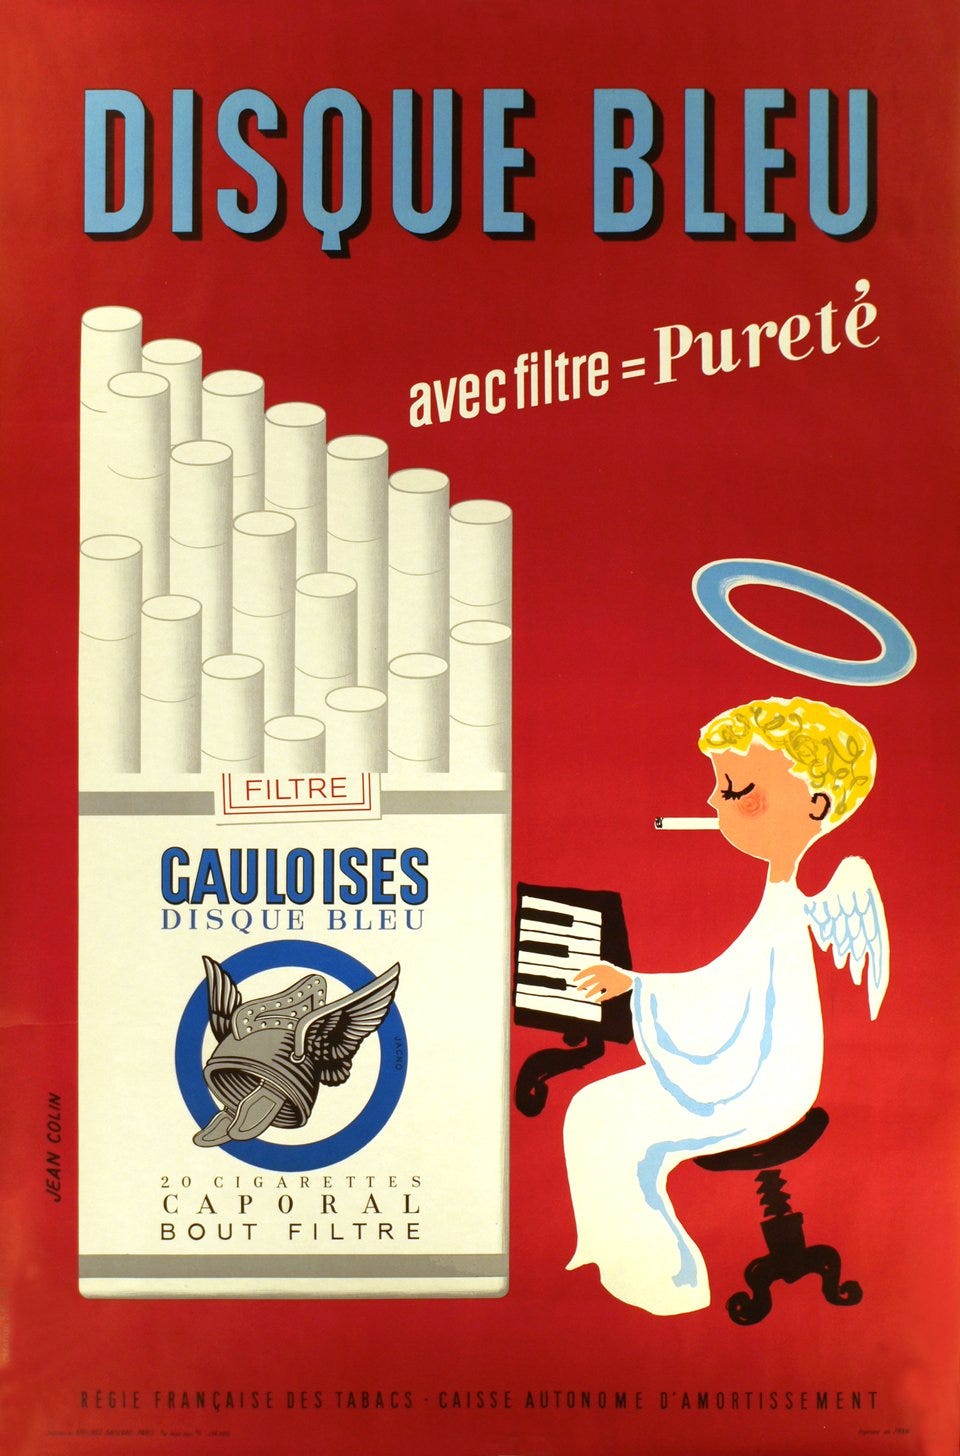
As Philip Morris brands grew in popularity in surrounding countries, slowly eroding local brand market shares, the company signed a licensing agreement with the Italian monopoly in 1962. By the end of the year, Philip Morris was exporting its cigarettes to 104 countries, and its brands were manufactured and marketed in 13 countries by licensees. Then, in 1963, the company struck gold. FTR, the Swiss concern originally licensed to produce PM products in 1957, became available for purchase, allowing Philip Morris to acquire an interest in the business. The company’s 1963 report highlighted the significance (emphasis added in bold):
The single most important international event of the year was the acquisition of a substantial Interest in Fabriques de Tabac Reunies S.A. — our licensee for the past seven years in Switzerland—which gives Philip Morris in a highly manufacturing operation on the Continent for the first time. In Switzerland, Marlboro is the second leading seller, and Fabriques de Tabac Reunies S.A. is the second largest cigarette manufacturer.
Philip Morris did not slow down, continuing to either strike licensing deals or expand owned production throughout countless geographies. One of the most notable was its acquisition of a majority interest in the Argentinian manufacturer Massalin y Celasco. The following year, 1967, would capture the rapid ascent realized so far. The year marked the company’s reorganization into Philip Morris Incorporated, comprising three distinct segments: Philip Morris Domestic, Philip Morris International, and Philip Morris Industrial. With this reorganization, Joseph F. Cullman III’s role(s) changed from President and CEO to Chairman and CEO.
Philip Morris Industrial, made up of Milprint Inc., Nicolet Paper Company, and Polymer Industries, experienced two significant worker strikes that year, dampening the segment’s profitability. However, cigarettes were still delivering head-spinning numbers. International sales increased by over 26% from the year prior. The segment’s unit sales were ~44 billion, which was equal to what the entire business, domestically and internationally, moved in total just a decade prior, in 1957. And if that wasn’t impressive enough, the company’s 1967 Annual Report elaborated on the stellar domestic performance (emphasis added in bold):
During the year we continued to outpace the industry in sales growth, earnings growth and penetration of the cigarette market both within and outside the United States. Cigarettes were again the most important contributor to the Corporation's sales and profits with sales of our cigarettes, here and abroad, continuing to increase well in excess of the population growth rate, notwithstanding significant tax increases on cigarettes both here and in most of our affiliate countries overseas. Total United States industry unit sales are estimated to have increased about 1.5 percent in 1967 as contrasted with our gain in domestic unit sales of 16 percent. Filter cigarettes continued to increase in popularity throughout the world and this trend is favorable for Philip Morris Incorporated because of our strong position in filters.
Marlboro contributed significantly to the year’s performance. In the domestic market, the company had just released Marlboro 100’s.

Philip Morris continued its string of innovation, and, four years later, in 1971, released the acclaimed Marlboro Lights. That year, Marlboro was firmly the #1 U.S. brand in international sales. Highlighting Philip Morris International’s success, Marlboro became the #1-selling global brand in 1972. Three years later, it became the #1 brand in the United States, holding 15.2% market share. Within the Marlboro mix, Marlboro Lights and Marlboro Menthol accounted for 21% of all Marlboros sold in the United States.
Joseph F. Cullman III retired in 1978 after serving as CEO for 21 years. From rebirthing Marlboro to establishing a global culture of excellence, his contribution to Philip Morris is difficult to overstate. If we are to reduce his tenure to the cold, hard numbers, what we see is astounding.
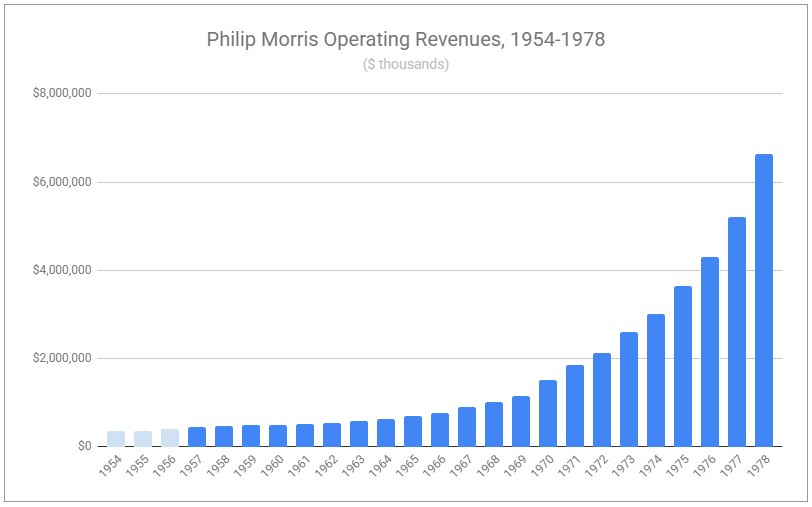
In 1956, the year before Cullman became CEO, Philip Morris recorded revenues of $410 million. By the time he retired in 1978, revenues had grown sixteenfold to $6.6 billion. During his leadership, revenues never experienced a down year.
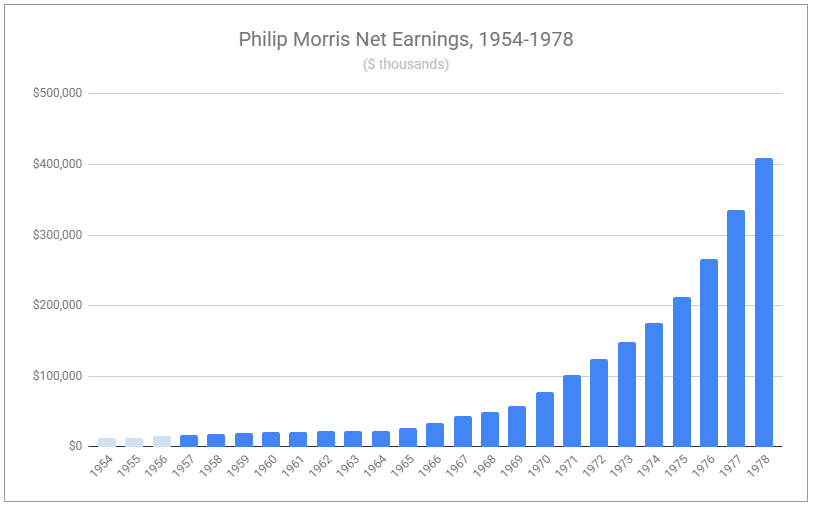
I believe we should be cautious when using revenues as a metric for success. After all, international expansion led to many sales, which were inherently of much lower margins than those experienced domestically. But if we look at net earnings, Cullman’s exceptionalism is only reinforced. Net earnings grew from $15.5 million in 1956 to $408 million in 1978; up more than 2500%. Reframed, 1978’s net earnings were nearly equivalent to the company’s 1956 revenues.
Making the growth rate in net earnings even more impressive is the fact that Philip Morris was spending more heavily on capital expenditures. For most of the first decade following the relaunch of Marlboro, the company was spending ~2% of revenue on capital expenditures. However, following 1970, that figure rose considerably, reaching 8.5% in 1978. That year’s Annual Report addresses the increase:
To meet demand and prepare for future growth in all of our businesses, we have invested more than $1.5 billion in capital expenditures over the five-year period from 1974 through 1978, of which $566 million was spent in 1978. The anticipated continued growth of the company, our constant emphasis on the high quality of all our products, and our efforts to maximize our production efficiency will require an even larger capital investment program over the next five years . For the period from 1979 through 1983, we estimate total capital expenditures will be somewhat in excess of $3.0 billion. More than 90% of this amount will be used to increase capacity and productivity to meet expected demand.
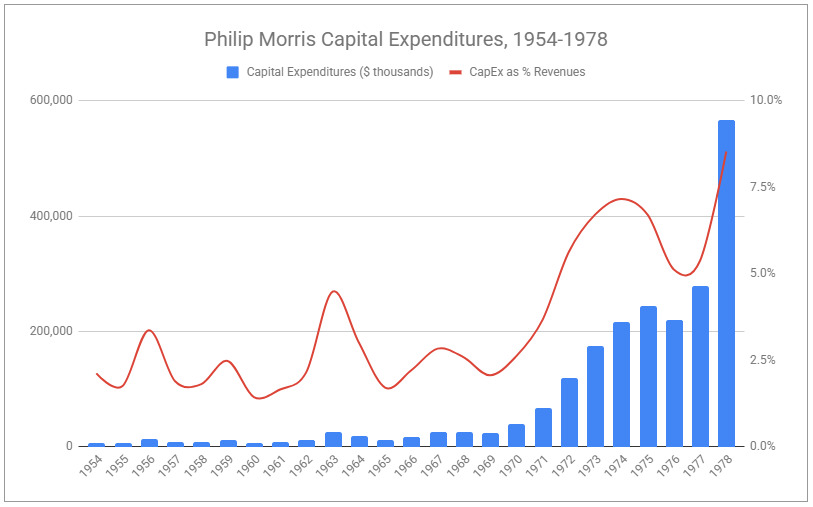
The tobacco business was still growing quickly, especially internationally. Part of the rise in capex was related to this, and it accelerated as the company began to favor owned production over licensing. However, a third story was being written at the same time. Much like its domestic competitors, Philip Morris could not shake the uncertain regulatory future facing its core business, leading to a string of unrelated acquisitions. Some where succesful. Others dreadful. As a whole, these ambitions demanded increasing amounts of capital.
Part Three concludes our exploration beyond the borders of the United States.
In Part Four, we will venture beyond tobacco entirely.
If you enjoyed this piece, hit “♡ like” on the site and give it a share.
Questions or thoughts to add? Comment on the site or message me on Twitter.
Ownership Disclaimer
I own positions in Altria and other tobacco companies such as Philip Morris International, British American Tobacco, Scandinavian Tobacco Group, and Imperial Brands. I also own positions in Haypp Group, a major online retailer of reduced-risk nicotine products.
Disclaimer
This publication’s content is for entertainment and educational purposes only. I am not a licensed investment professional. Nothing produced under the Invariant brand should be thought of as investment advice. Do your own research. All content is subject to interpretation.
Additional resources:
Cullman, Joseph F. III. I’m A Lucky Guy. 1998.
Philip Morris Annual Report, 1954. Source
Philip Morris Annual Report, 1955. Source
Philip Morris Annual Report, 1956. Source
Philip Morris Annual Report, 1960. Source
Philip Morris Annual Report, 1962. Source
Philip Morris Annual Report, 1963. Source
Philip Morris Annual Report, 1966. Source
Philip Morris Annual Report, 1967. Source
Philip Morris Annual Report, 1971. Source
Philip Morris Annual Report, 1972. Source
Philip Morris Annual Report, 1975. Source
Philip Morris Annual Report, 1978. Source
Hi Devin - Fascinating Part 3 piece & no doubt that Joseph F. Cullman III was a dynamo CEO from 1956 - 1978. Taking Philip Morris to where their 1978 Earnings were nearly equivalent to their 1956 Revenues, is truly remarkable.
Enjoyed the 1960’s French Gauloises Cigarette ad showing an angel puffing away on a cigarette while playing an organ. I’m sure the Pope was thrilled.
Also liked Cullman III recalling how the Aussies in 1959 nicknamed PM’s Dunhill cigarettes as “Dunghill”. It reminded me of my high school days in the 1970’s when a group of Aussie foreign exchange students came over & I was amazed how some of them could drink an entire case of Miller Lite beer & still seem relatively cognitive. When I asked them about this, they simply said drinking Miller Lite was like drinking “weasel piss” & nothing like the full body beer they were use to drinking in Australia. Leave it to the Aussies to share their unfiltered feelings about some American products.
Looking forward to your Part 4 post on Philip Morris. Thanks